Generally eligible
- Individual taxable brokerage accounts
- Joint taxable accounts
- Revocable and irrevocable trusts
- S corporations
Everything an advisor needs to evaluate a 351 ETF exchange: the statute behind it, the diversification tests a client portfolio has to pass, what can and cannot be contributed, how a launch runs, and when it beats the alternatives.
Educational content for financial professionals. Not tax, legal or investment advice.
Section 351 of the Internal Revenue Code lets an investor contribute property to a newly formed corporation and receive its stock without recognizing gain. Applied to ETFs, a group of investors contributes appreciated securities into a brand-new fund at launch and receives ETF shares in return. Because nothing is sold, no capital gain is recognized at the transfer — and every contributed tax lot keeps its original cost basis and holding period.
A 351 exchange is the 1031 for equities: swap a portfolio of appreciated stocks and ETFs for shares of a new ETF, and defer the gain instead of paying it.
"We are not selling your stocks. They move into a new fund and you get fund shares back — same cost basis, same holding period, no tax bill this year. If you sell the fund later, the gain is still there."
The ETF seeding use case is roughly five years old and, until recently, ran through a handful of sponsors. Volume tripled in 2025. See adoption data.
Two from the Internal Revenue Code, one from the SEC. Each removes a different tax or regulatory obstacle; the transaction needs all three.
Recharacterizes the transfer as a capital contribution rather than a sale. Tax liability is deferred, not erased.
Authorizes custom baskets, giving the receiving fund standing authority to accept a bespoke basket of contributed securities in kind.
Lets the fund satisfy redemptions in kind without triggering fund-level capital gains — the reason the ETF wrapper stays tax-efficient afterward.
Scrutiny rises as volume rises. Two patterns draw it in particular: stuffing, where off-strategy or unwanted assets are pushed into a fund, and sequential seeding, where a wrapper exists mainly to deliver deferral. Three practices keep a file defensible.
Assess each investor's portfolio against the tests rather than assuming it clears.
Keep records showing why each contribution was made and how it was tested.
Contributed baskets must match the fund's stated strategy, including the Names Rule 80% floor.
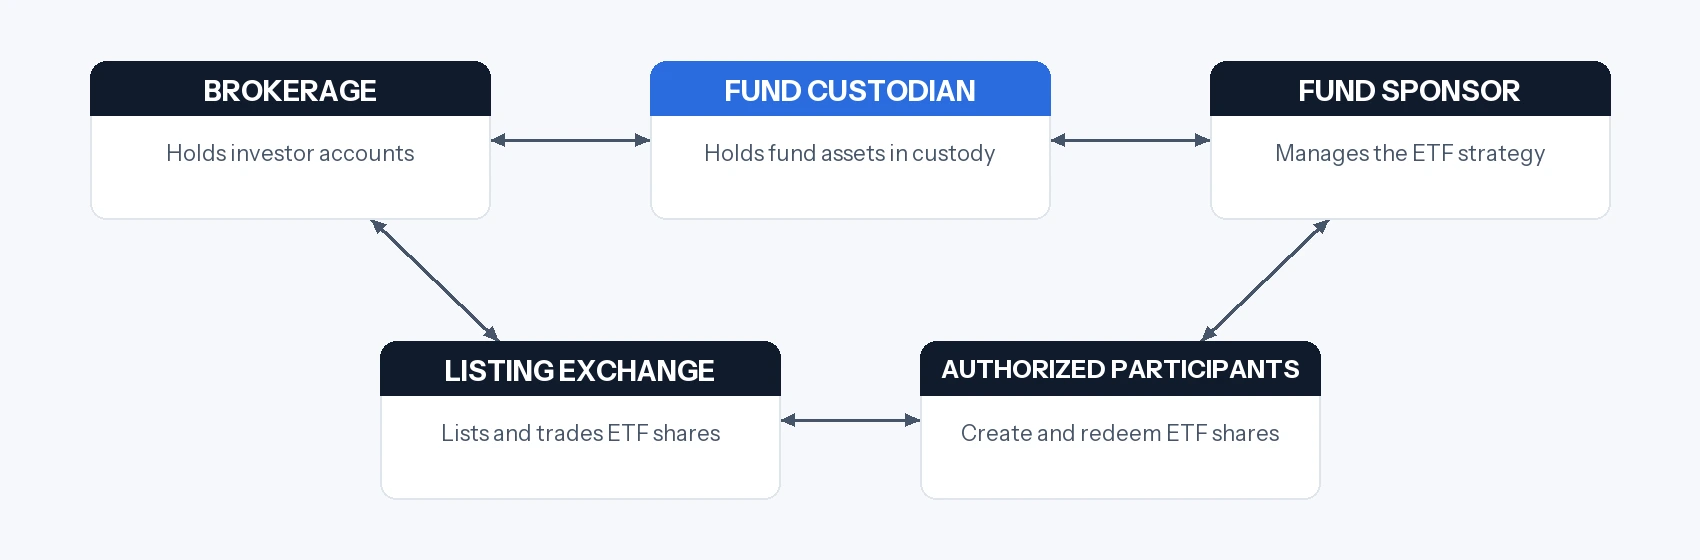
A diversified basket transfers in kind from the client's brokerage account to the new fund's custodian. Nothing is sold.
Shares are issued at the same market value as the contribution and delivered back to the same custody account.
Each original tax lot survives intact — same cost basis, same acquisition date — now attached to one ticker instead of many.
The fund trades on a major exchange under the 1940 Act, rebalancing internally without passing gains to shareholders.
Advisors own the first test. The sponsor owns the second. A portfolio can clear the investor test and still be trimmed for fund-level reasons.
No one security may exceed 25% of the contributed portfolio's market value.
The five largest positions combined may not exceed 50% of contributed value.
A basket of only individual stocks needs at least 11 names to satisfy both limits.
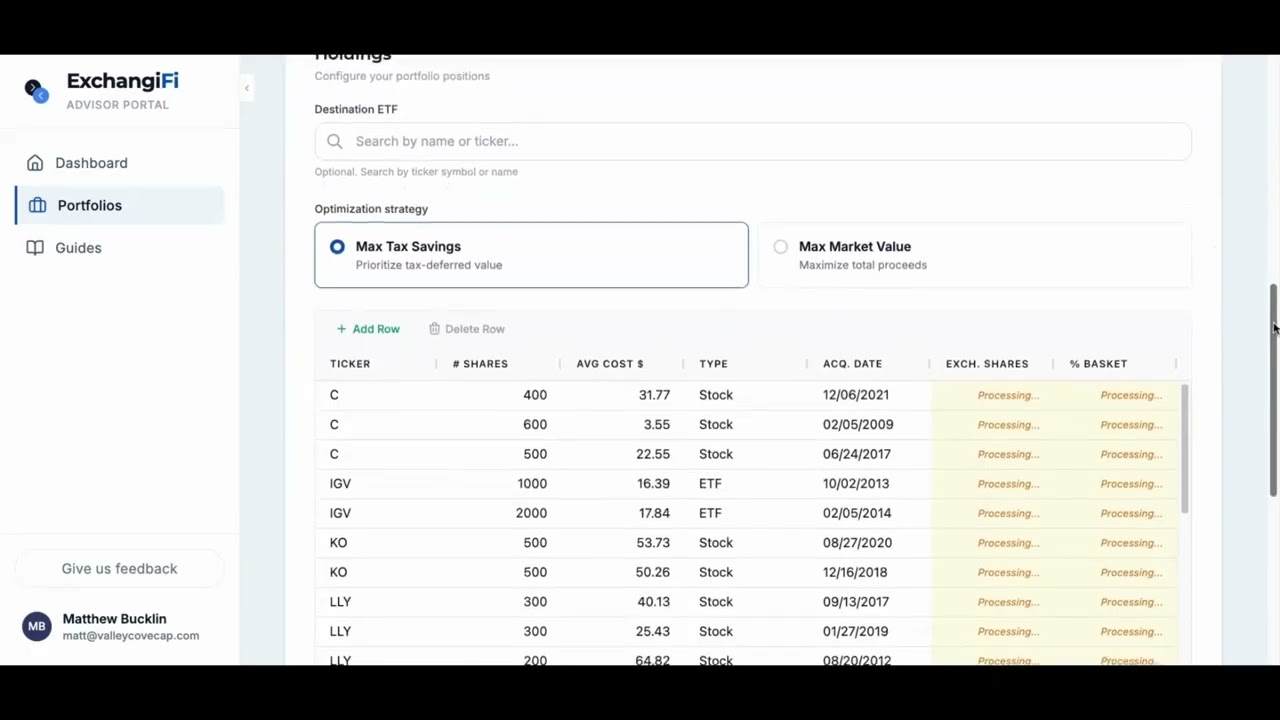
The exchange executes at the tax lot level. For each contributing taxpayer, lots are pulled from every account they contribute from — taxable, joint, trust — and combined into one contribution. Diversification is tested on that total, never account by account. At any real book size this is not a spreadsheet exercise.
An ETF or closed-end fund is never tested as a single position. The test looks through to its underlying holdings, and multiple share classes of the same issuer combine into one position.
Across the whole fund — not per investor — the aggregate portfolio must satisfy regulated investment company diversification: the 25/50 and 5/50 concentration limits, plus the 3/5/10 limits on the fund's ownership of other funds. Sponsors also hold to the Names Rule, which requires at least 80% of assets to match the fund's stated focus, and generally accept only liquid, intraday-traded securities.
Contributing investors must collectively own at least 80% of the new fund's voting shares immediately after the exchange. No single investor needs 80% — it is a group threshold, and all contributions must close simultaneously to count. If the threshold is missed, the exchange is taxable for everyone in it. Coordinating the group is the sponsor's job.
The general rule: liquid securities that trade intraday on an exchange qualify. Search a holding type below, or filter by status.
No holding type matches that search.
Eligibility ultimately depends on the receiving fund’s strategy and your custodian. Ask before you assume.
General guidance only. Final eligibility depends on the receiving fund’s strategy, custodian capabilities and the Section 351 requirements. Confirm every borderline holding with the sponsor before the deadline.
Every position needs cost basis and acquisition date. Missing history can disqualify a lot or the whole contribution.
Fractional shares generally cannot be contributed and must be removed from the account beforehand.
Sponsors commonly require the contributing account to hold only the securities being transferred.
A minimum cash cushion is often required so each investor can be delivered whole ETF shares.
Signed by the client and governed by the custodian, not the sponsor. Timelines vary — start early.
Sponsors monitor diversification daily up to the seed date, which requires visibility into the account.
Participation is limited to US persons, and the benefit only exists where capital gains tax would otherwise be owed on a sale. Account type drives the answer.
Retirement accounts are excluded for a simple reason: there is no capital gain to defer, so the exchange adds nothing. Some custodians also require the contributing account to sit under an advisory relationship — check before you promise a client a slot.
A 60-second screen before you pull tax lots. It is educational, not a compliance determination — the real test runs at the position level.
This screen looks at the four things that most often stop a contribution: account type, concentration, what the account holds, and whether the tax lots exist.
Nothing here blocks a Section 351 contribution. The next step is the position-level test: aggregate every tax lot for this taxpayer, apply look-through to any funds, and check the basket against the receiving fund’s strategy.
At least one answer points to something to fix before this portfolio can be contributed: usually trimming a position, clearing ineligible holdings out of the account, or rebuilding tax lot records.
Retirement accounts have no gain to defer, so the exchange adds nothing. A portfolio made up mostly of private or illiquid holdings has nothing contributable. A different tax-aware strategy is the better conversation.
ExchangiFi's software runs the 25/50 test across every tax lot and account with live prices and daily fund holdings, applies look-through, and reports the eligible portfolio that maximizes taxes deferred.
Run a portfolioFrom the investor’s perspective. Dates are sponsor-specific, but the sequence is consistent.
The registration statement goes effective and the fund is marketed to advisors and investors.
Participation agreements are signed, portfolios are built and tested, documents are reviewed.
A trading freeze begins and shares move from the brokerage to the fund's custodian.
Final diversification testing, NAV is struck, ETF shares are created and begin trading.
ETF shares are transferred back into the client's brokerage account.
Cost basis overrides reach the broker and carried-over tax lots appear in account records.
Two dates matter most to an advisor: thecontribution deadline, after which no new portfolios are accepted, and the start of thetrading freeze, after which contributed positions cannot be traded. Both sit weeks ahead of the launch date.
Six situations where a taxable sale is the obstacle and an in-kind contribution is the way around it.
An outsized position built through employee purchase plans or decades of appreciation. Contribute part of it alongside the rest of the book and cut the weight without triggering the gain.
Several separately managed accounts collapse into one ticker. Less administration, fewer per-account trades, lower total fees, deferral intact.
Years of harvesting leave a portfolio narrow and fully appreciated with nothing left to sell. A 351 exchange re-indexes it and lets rebalancing continue inside the fund.
A holding is being acquired for cash or a fund is scheduled to liquidate. Exchanging before the deal closes avoids a gain the client never chose to realize.
Positions scattered across brokerages and other advisory firms come together into one holding — and one relationship.
A shift from growth to income near retirement, or fragmented family holdings unified so beneficiaries inherit one diversified position with carryover basis.
Concentration risk is the most avoidable portfolio risk. Taxes are the most controllable cost.
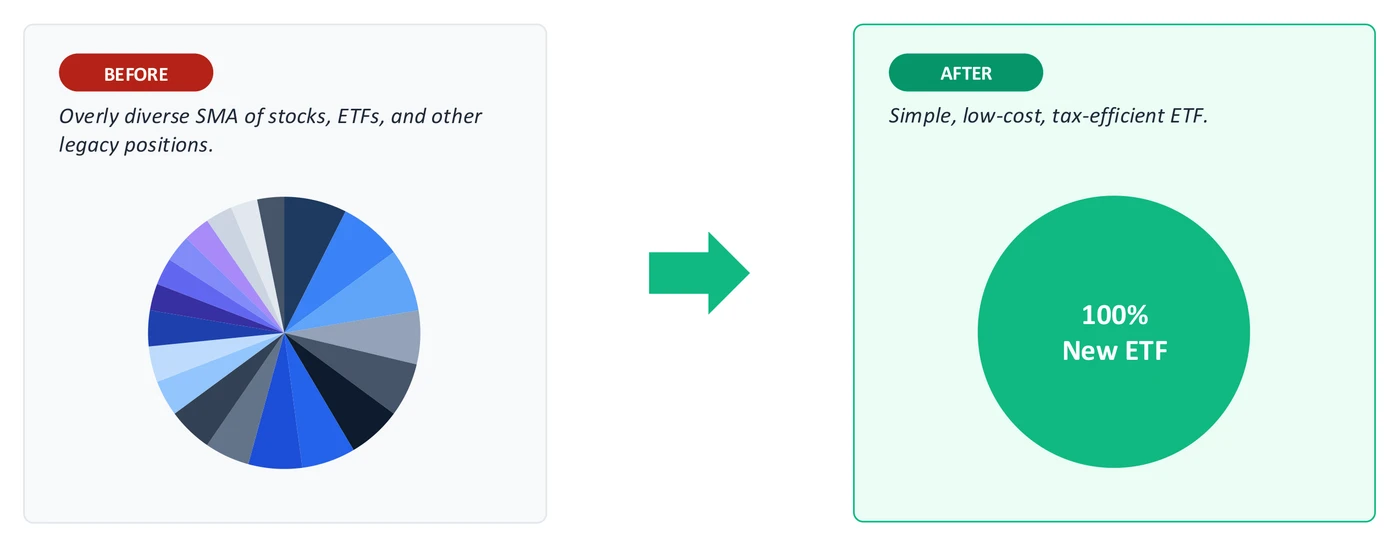
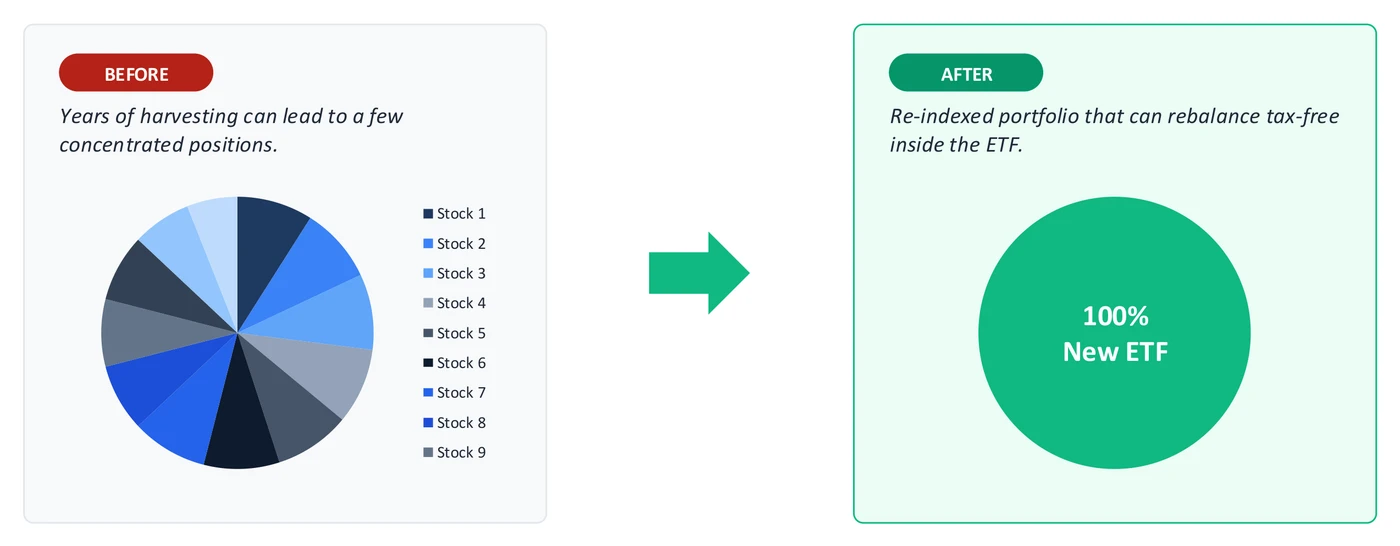
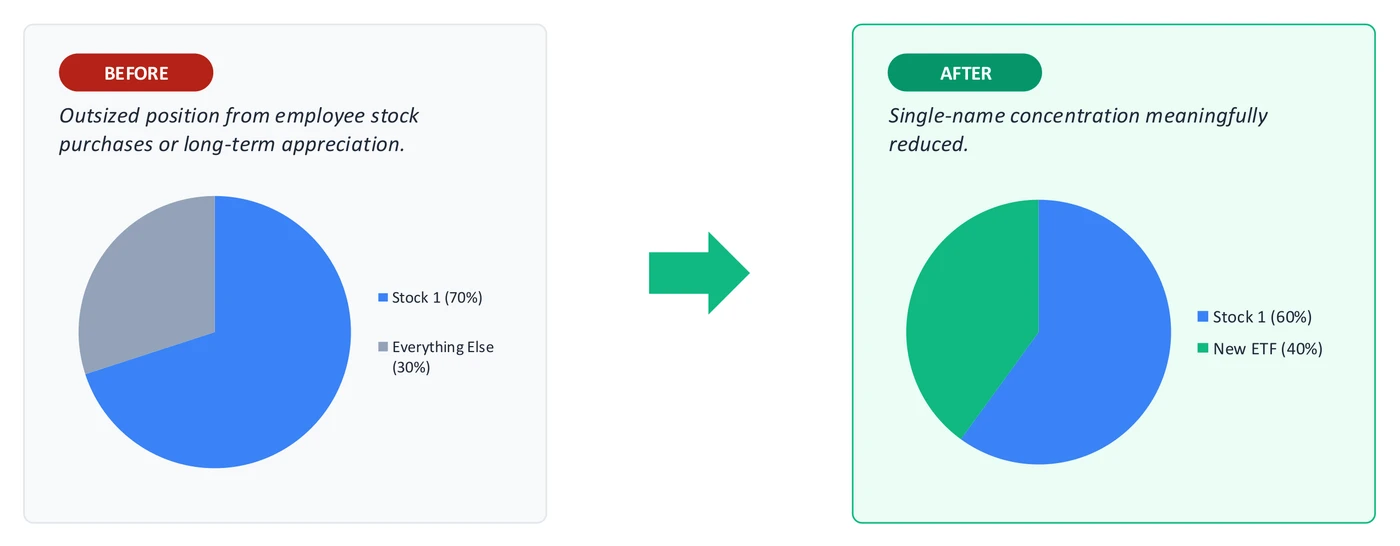
Illustrative of an actual engagement. Results depend on portfolio composition, basis and eligibility.
The most common confusion in this category. A 351 exchange moves a diversified portfolio into a better wrapper; an exchange fund diversifies a concentrated one. They solve different problems.
Answer three questions and see which route fits
Illustrative prototype for education — not tax or investment advice. Best viewed on a desktop screen.
Source:351.tax, the public registry of in-kind ETF launches by individual investors. Figures include known filings plus estimates across funds pending N-CSR.
0 of 12 complete
Educational overview for advisors and investors · PDF, 19 pages
The statute, the SEC rules and the qualification tests in full · PDF
Twelve steps from first conversation through post-launch reporting
Advisors, issuers, service providers and counsel comparing notes
Section 351 of the Internal Revenue Code lets an investor contribute property to a newly formed corporation and receive its stock without recognizing gain. Applied to ETFs, a group of investors contributes appreciated securities to a brand-new fund at launch and receives ETF shares in return. No sale occurs, so no capital gain is recognized at the transfer, and each contributed tax lot keeps its original cost basis and holding period.
No. Section 351 has been part of the Internal Revenue Code since 1954. Congress added it because reorganizing a business into a corporate structure produced no real economic gain and should not have been taxed as if it did. What is new is the application: using the same provision to seed a newly launched ETF with contributed securities. The first syndicated in-kind ETF launches by individual investors date to 2021.
No. It defers the tax. Cost basis and holding period carry over to the ETF shares, so the embedded gain travels with the position and is recognized when the shares are eventually sold. The advantage is compounding from a higher base, and the option to hold until a step-up in basis at death.
Generally no. Section 351 requires a contribution to a newly formed corporation, so the opportunity exists only in the window around a new fund's launch. Once the fund is trading, new shares are created through the normal ETF creation process, which is not a Section 351 transaction.
Investors diversify on a tax-deferred basis and keep assets in a liquid ETF structure. Advisors gain a high-value tax service, often consolidating held-away assets and avoiding the AUM erosion a taxable sale would cause. Issuers cover launch costs and reach scale from day one.
Measured against each contributing taxpayer's aggregated portfolio at the time of contribution: no single position may exceed 25% of contributed market value, and the five largest positions combined may not exceed 50%. A basket of only single stocks therefore needs at least 11 holdings. Many sponsors apply tighter internal limits, such as 22% and 47%.
An ETF or closed-end fund is not tested as a single position. Diversification looks through to its underlying holdings. A 30% position in a large-cap ETF that holds 7% Apple contributes 2.1% Apple to the test, which is then added to any Apple held directly or through other funds. Multiple share classes of the same issuer are combined into one position.
Yes. The exchange executes at the tax lot level, and lots are pulled from every account the taxpayer contributes from — taxable, joint, trust and so on — then aggregated into a single contribution per taxpayer. Diversification is tested on that aggregated total, not account by account.
A 351 exchange is not built to fix concentration on its own, because the contributed basket has to be diversified before it goes in. What often works is contributing part of the concentrated name alongside the rest of the diversified book, which lowers the weight without triggering the gain. If one name dominates the balance sheet, an exchange fund is usually the better tool — sometimes both are used together.
No. Cash is not a contributable security and does not count toward the tests. Sponsors often ask that a small cash balance remain in the contributing account so each investor can be delivered whole ETF shares rather than a fraction.
Taxable accounts of US persons: individual and joint brokerage accounts, most trusts, and S corporations. LLCs, partnerships and C corporations generally require additional review. Retirement accounts such as IRAs and 401(k)s are not eligible because there is no capital gain to defer. Some custodians also require the account to sit under an advisory relationship.
The advisor assembles positions and tax lots, tests the basket for diversification and eligibility, submits the portfolio and documents through the sponsor’s portal, and coordinates the custodian letter of authorization. The client reviews and signs the paperwork, understands that the fund’s strategy replaces their holdings, and leaves the positions untouched through the freeze.
Fund sponsors typically absorb the administrative cost of facilitating the exchange. The ongoing cost is the new ETF's expense ratio, which for 351-seeded funds has generally run between roughly 0.45% and 1.50% depending on strategy and manager.
A syndicated launch typically runs three to six months from marketing to trading. Onboarding and portfolio review happen one to three months before launch, securities transfer to the fund custodian one to two weeks out, ETF shares are delivered back within one to two business days of launch, and carried-over tax lot information reaches accounts within roughly two weeks.
Immediately. Shares trade on an exchange from the first trading day, with no lockup and no redemption restrictions. Selling realizes the deferred gain, because basis and holding period carried over.
It varies by sponsor. Schwab and Pershing are commonly supported on the brokerage side, with fund custody often at a bank such as U.S. Bank. Every client signs a letter of authorization issued by their own custodian, and those timelines are set by the custodian rather than the sponsor — start early.
Unchanged in substance. If a client contributed three ETFs across six tax lots, they hold one ETF with the same six lots — each keeping its original cost basis and acquisition date. Custodians do not all treat carried-over lots identically, so confirm post-transaction reporting with yours.
The contribution can be recharacterized as a taxable sale, triggering capital gains tax for the contributing investor. Because the control test is a group threshold, a failure at the fund level affects everyone in the transaction. That is why eligibility testing, documentation and strategy alignment happen before the deadline, not after.
Recharacterization as a taxable sale if the requirements are not met. New fund risk, since the receiving ETF has no operating history and no guarantee of reaching viable scale. Strategy risk, because the client ends up holding the fund’s strategy rather than their prior positions. And the possibility that tax law, IRS guidance or industry interpretation changes.
An exchange fund diversifies a concentrated single-stock position through a private partnership with roughly a seven-year holding period and about 20% in qualifying illiquid assets, limited to accredited investors or qualified purchasers. A 351 exchange moves an already diversified portfolio into a new ETF that trades on-exchange from day one with no lockup, generally open to US taxpayers. Different problems, and sometimes used together.
Volume tripled in 2025, and attention has followed. Two patterns draw the most: stuffing, where off-strategy or unwanted assets are pushed into a fund, and sequential seeding, where a wrapper exists mainly to deliver deferral. Deliberate eligibility analysis, documented rationale and genuine strategy alignment are what keep a file defensible.
No question matches that search.
Ask us directly at [email protected].
ExchangiFi runs the 25/50 test across every tax lot and account, applies look-through with daily fund holdings and live prices, and reports the eligible portfolio that maximizes taxes deferred — output built to walk through with a client.
New launches, deadline reminders and regulatory developments. No more than twice a month.
A Section 351 exchange is intended to qualify as a tax-deferred contribution rather than a taxable sale. If the transaction fails to satisfy IRC Section 351, related provisions or the SEC requirements applicable to the receiving fund, it may be recharacterized as a taxable sale, triggering capital gains tax for the contributing investor. Tax deferral is not tax elimination: the original cost basis and holding period carry over and the gain remains embedded until the shares are sold.
This page summarizes ExchangiFi’s understanding of Section 351 ETF exchanges as of the date shown. The relevant tax code, SEC rules, IRS guidance and industry interpretation are subject to change, and reasonable practitioners may read them differently. Eligibility, deal terms and outcomes vary by fund sponsor, custodian and the specific facts of each contribution.
ExchangiFi is a technology company. We provide software that helps wealth managers, advisors and ETF sponsors evaluate and coordinate in-kind contributions of securities. We are not an investment adviser, broker-dealer, law firm or accounting firm. Nothing on this page is investment advice, a recommendation to buy or sell any security, a legal opinion or tax advice, and nothing here is an offer to sell or a solicitation of an offer to buy any security. All investing involves risk, including possible loss of principal. Past performance does not guarantee future results. Consult qualified tax and legal counsel before contributing assets in reliance on Section 351.